
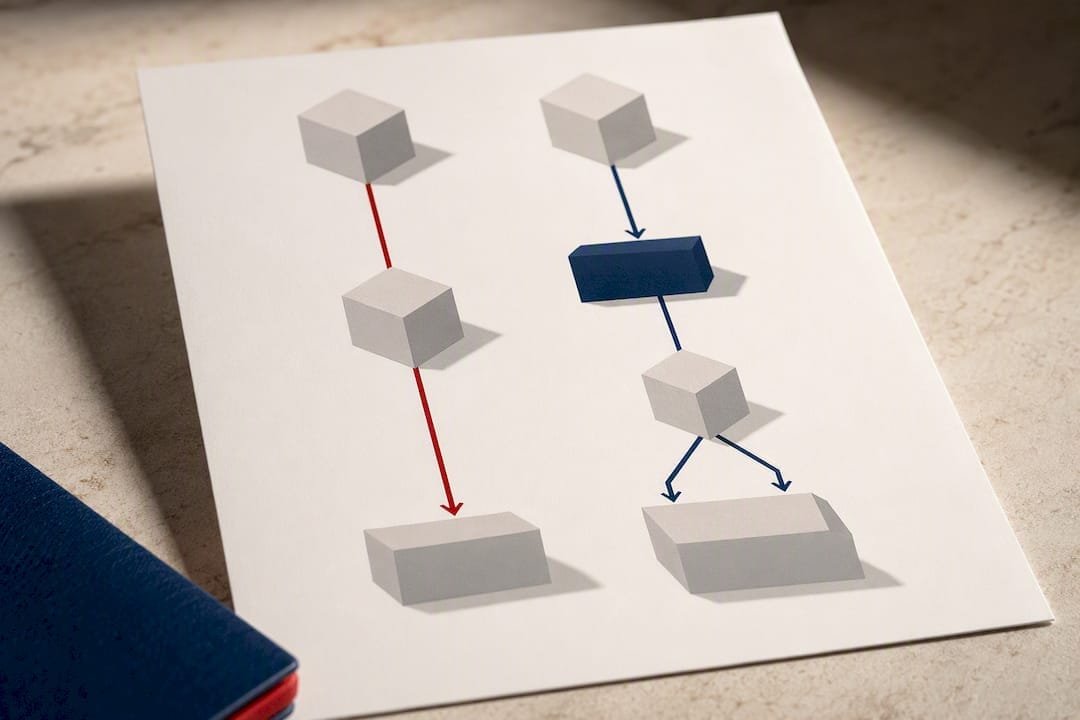
A disregarded entity (SMLLC) transfers direct profits to the owner's tax return; a C-Corp is taxed separately, as a separate legal entity.
For most Brazilian entrepreneurs who are not seeking venture capital or intend to retain profits within the American company, the disregarded SMLLC (Small, Medium, and Large Liability Company) is usually the simplest and cheapest structure to maintain.
In summary:
- A disregarded SMLLC transfers profits directly to the owner's tax return, while a C-Corp pays separate taxes on its earnings.
- The tax classification is determined by the IRS after incorporation, influencing taxation regardless of the state legal form.
- The C-Corp structure is more expensive if the main objective is to withdraw profits frequently, due to double taxation on dividends.
- Without an income tax treaty between Brazil and the US, the choice should prioritize simplicity and predictability of tax credits when planning profit distribution.
- Changing from a disregarded entity to a C-Corp entity requires careful assessment of the tax impact and accounting planning, preferably with expert guidance.
Naventia
Choose your structure with more clarity.
Naventia advises Brazilian companies on tax, legal, and operational aspects of expanding into the American market.
Meet Naventia
Index
- Disregarded entity vs. corporation: the differences established by state law and the IRS.
- How much tax do you pay on each structure?
- How does Brazil-US double taxation affect your choice of tax structure?
- How to migrate from a disregarded entity to C-Corp
- What to ask before deciding between a disregarded entity and a corporation
- What does Naventia see in the most common mistakes regarding this decision?
- Consulting services to help you choose between a disregarded entity and a corporation.
- Sources
- Frequently Asked Questions
Disregarded entity vs. corporation: the differences established by state law and the IRS.
The difference begins with the company's constitution, but is only completed with the federal tax classification. You form the company. second The chosen U.S. state law: an LLC or a corporation.
Only after that does the IRS decide how that entity will be treated for income tax purposes.
One single member LLC (SMLLC) It is, by default, an entity that is disregarded.
This means that it does not exist as a separate taxpayer from the owner for federal income tax purposes.
Already corporation (C-Corp) By legal definition, it is created as a distinct legal entity, with its own CNPJ (the American equivalent is the EIN) and the obligation to declare its own results.
This distinction leads to different practical consequences:
- SMLLC does not file its own income tax return; the result is reported directly on the owner's personal tax return.
- AC-Corp files Form 1120 and pays corporate income tax on profits before any distribution, in accordance with applicable law.
- State law defines the governance structure and limited liability; federal law (via check-the-box rules) defines only how profit is taxed.
- You can have an LLC incorporated in Delaware and still choose to tax it as a corporation via federal election, without changing its state legal nature.
Understanding this separation between legal form and tax classification avoids the most common mistake among Brazilian entrepreneurs: thinking that "opening an LLC" and "being taxed as an individual" are the same decision. They are not. State law creates the framework; the IRS decides what happens within it.
How much tax do you pay on each structure?
The real tax impact appears in the cash flow, not in the entity's name. In disregarded SMLLC, all profit goes directly to the owner's personal tax return and is taxed at the progressive personal income tax rate in the US, in addition to self-employment tax, which covers Social Security and Medicare.
There is no intermediary corporate tax; the money flows only once.
At C-Corp, the approach is different and more expensive in distribution scenarios. The company pays corporate income tax on profits.
If this profit is then distributed as a dividend to the shareholder, a tax applies. second Personal income tax.
This is known as double taxation, and it weighs heavily on those who intend to frequently withdraw cash from the company instead of reinvesting it.
Pro tip: Excessive retention of profits within a C-Corp without business justification can lead to additional IRS penalties for improper capital accumulation — model the distribution flow before choosing this structure.
Some operational aspects deserve extra attention:
- Even though it is not considered for income tax purposes, a SMLLC needs an EIN and is treated as a separate entity for payroll purposes and certain excise taxes, as per IRS guidelines.
- Hiring employees in the U.S. generates payroll obligations independent of the entity's tax classification.
- AC-Corp needs to maintain more rigorous corporate accounting, including minutes and formal registration of distributions.
The underlying rule is simple: the more profit you plan to extract from the American company in the short term, the more expensive the C-Corp structure becomes due to double taxation.
How does Brazil-US double taxation affect your choice of tax structure?
Brazil and the United States do not have an income tax treaty in effect, which completely changes the calculation of tax risk for those who live in Brazil and earn income in the US.
Without a treaty, you rely on unilateral mechanisms to avoid paying double taxation on the same income, according to an analysis of double taxation between Brazil and the US.
In practice, it works like this:
- Brazil offers reciprocal credit on taxes paid abroad, and the US allows foreign tax credit in specific situations, but the two systems do not automatically communicate with each other.
- The social totalization agreement between the two countries, in effect since 2018, avoids double social security contributions between INSS (Brazilian National Institute of Social Security) and Social Security. Without this agreement, you would pay contributions in both countries for the same work.
- The absence of a bilateral investment treaty also limits formal protection instruments between the two governments, according to data from... U.S. Department of State.
The taxation of dividends in Brazil, with recent changes, makes the decision between SMLLC and C-Corp even more sensitive to the planned distribution flow.
If the profit leaves the American company as a personal withdrawal (SMLLC) instead of a formal dividend (C-Corp), the way it is recognized in Brazil changes.
Without an income treaty between the countries, the choice of structure should prioritize predictability of tax credits and simplicity of cash flow, not the pursuit of a supposedly more advantageous regime.
One survey on double taxation of LLCs It details the four points that generate the most doubt in this tax intersection.
How to migrate from a disregarded entity to C-Corp
Changing tax classifications requires Form 8832, and the timing of this election has effects that go beyond simply filling out the form.
- Evaluate the real reason for the change. Seeking institutional investment, creating classes of shares, or retaining profits in a structured way are typical justifications for electing C-Corp.
- Simulate the impact of the deemed liquidation. The election can be treated, for tax purposes, as if the previous entity were liquidated and a new corporation were created in its place, which could generate immediate taxation on unrealized gains, according to an analysis by The Tax Adviser.
- Confirm the expiration date. The election can be postponed for up to 75 days or scheduled for up to 12 months in the future, depending on the filing date.
- Separate accounts and accounting before filing. AC-Corp requires its own corporate registrations from the first day the election takes effect.
Pro tip: Never file Form 8832 without first modeling the tax implications of the deemed liquidation with an accountant who also understands the Brazilian side of your business structure.
What to ask before deciding between a disregarded entity and a corporation
The right answer depends less on the entity itself and more on the financial behavior you plan to have in the coming years.
Before deciding, answer these questions honestly:
- Do you intend to retain profits within the American company for more than a year, or will you withdraw cash regularly?
- Is there a concrete plan to seek institutional investors or venture capital funds in the US?
- Does your operation depend on enhanced asset protection, with a clear separation between personal and business assets?
- Has the Brazilian accountant who handles your tax return ever worked with income from a disregarded American entity?
Some signs clearly indicate the need to migrate to C-Corp:
- Institutional investors require a structure of preferred and common stock, something that LLCs do not natively offer.
- You plan to raise funding through SAFE or equity funding and need a formal cap table.
- The company will operate with multiple foreign and Brazilian partners with unequal and complex stakes.
When none of these signs appear, the disregarded SMLLC tends to reduce both the tax burden and annual bureaucracy in the US. Comparing LLCs, corporations, and holding companies helps to visualize this intersection of criteria in more detail.
What does Naventia see in the most common mistakes regarding this decision?
In practice, for those who follow Brazilian companies entering the US market, the most common mistake isn't choosing the wrong structure. It's choosing without simulating the real cash flow of the operation in the first two or three years.
Naventia works with specialists based in the United States precisely because tax classification decisions have an immediate effect on payroll, EIN, and compliance obligations that vary from state to state.
A recurring mistake: treating the American EIN as if it were equivalent to the Brazilian CNPJ, which generates confusion about which obligations actually apply to the disregarded entity.
Another common mistake is deciding on the structure before mapping out the fundraising plan and profit distribution profile, when it should be the other way around.
The right consulting firm comes in precisely here: modeling the tax scenario, indicating the most suitable state, and maintaining ongoing compliance after the opening.
— Flavio Inacarato
Consulting services to help you choose between a disregarded entity and a corporation.
Choosing between SMLLC and C-Corp without simulating the profit distribution flow is the most common cause of tax rework we see in Brazilian companies during their first two years of American operation.
This diagnosis should be structured before the company is formed: it is important to cross-reference the revenue projection, the fundraising plan (or lack thereof), and the tax situation in the country of origin to indicate whether the disregarded SMLLC or the C-Corp reduces taxes more in the specific case.
This includes opening the entity in the appropriate state, obtaining an EIN, opening a US bank account, and integrated international tax planning to avoid surprises when filing taxes.
If you are considering entering the American market in the coming months, the natural next step is to learn about... Naventia's strategic support for international expansion and schedule an initial diagnostic consultation before filing any documents in the U.S.
Sources
- Classifying business entities under the check-the-box regulations
- US Department of State — country investment/treaty notes
Frequently Asked Questions
What is a disregarded entity?
It is a company, usually a SMLLC (Small, Medium, and Large), that is not taxed separately from the owner: all profit is reported directly on the personal tax return, without any intermediary corporate tax.
How can I tell if my company is a disregarded entity?
If you formed an LLC with a single owner and never filed Form 8832 to elect taxation as a corporation, it is, by default, a disregarded entity under IRS rules.
Does Brazil have a trade agreement with the United States?
No. The two countries do not have an income tax treaty in force, although there has been a pension aggregation agreement since 2018 that avoids double contributions to INSS (Brazilian National Social Security Institute) and Social Security.
What is the purpose of an EIN in the US, and does it replace a CNPJ?
The EIN is the U.S. federal tax identification number, required even by disregarded entities to open bank accounts and meet payroll obligations. It does not replace the Brazilian CNPJ; they are registrations from different and independent tax systems.
Is it worth choosing C-Corp status just to appear more professional to investors?
No, not before simulating the cost of double taxation.
The election only pays off when there is a concrete plan for institutional fundraising or structured profit retention, as Naventia explains regarding the tax risks of LLCs.
Naventia
Talk about its structure in the US.
Send us your questions so we can understand the risks and plan the tax, legal, and operational structure of your company.
NNaventia
Send an email to contato@naventia.com